Fee-Only Plan Discussion with a CPA, CFP®
Retirement Plans for Northern Colorado Business Owners: 401(k), SEP & Cash Balance
Business owners can save for retirement through the business. Which plan type is available, and what it can defer, depends on facts and current law—not on a product sales pitch. Confirm current contribution limits and eligibility with your CPA or TPA. This page is educational and is not tax advice.
- Fee-only fiduciary — no commissions; the firm receives no portion of custodian commissions
- SEC-registered RIA (CRD #300811). Registration does not imply a certain level of skill or training.
- Dillon is a CPA and CFP® — tax questions and retirement-plan questions in one conversation
- Loveland office serving Northern Colorado business owners
CPA Coordination and Investment Advice
Choosing a business retirement plan involves tax rules and investment decisions. Dillon Goodman holds both the CPA and CFP® designations. Plan-design discussion can account for your tax situation, employee obligations, and personal retirement goals, and we can coordinate with your CPA or TPA. This is not a promise of a particular contribution amount or tax result.
Understanding Your Retirement Plan Options
Contribution limits, eligibility, and tax treatment change. Confirm current limits and rules with your CPA or TPA. The descriptions below are educational and do not constitute tax advice. We do not guarantee that any plan type will be available to you or will produce a stated deferral.
Named business-retirement-plan services on this site: SEP, SIMPLE, solo 401(k), and cash balance.
SEP-IRA
- Generally employer contributions only (typically no employee salary deferrals)
- Limits and coverage rules are set by current law; they can differ from a SIMPLE—confirm with your CPA or TPA
- Eligible employees may need to be covered on a proportional basis (plan and IRS rules apply)
- Who it may fit: some solo owners or small teams, depending on facts—not a determination that it fits you
SIMPLE IRA
- Generally employee salary deferrals plus an employer match or contribution
- Administrative cost compared with a 401(k) varies; it is not always lower
- Contribution limits are often different from a SEP or 401(k)—confirm current limits
- Eligibility is limited under current law (often described as 100 or fewer employees)—confirm current eligibility with your CPA or TPA
- Who it may fit: some small businesses that want employee deferrals—not a determination that it fits you
Solo 401(k)
- Generally for owner-only businesses (and a spouse), subject to current rules
- May allow employee deferrals plus employer profit-sharing contributions
- Combined limits compared with a SEP or SIMPLE depend on current law and facts—confirm with your CPA or TPA
- Who it may fit: some self-employed owners with no employees other than a spouse—not a determination that it fits you
Cash balance pension plan
- A defined-benefit design with individual hypothetical accounts
- In some cases, deductible contributions can be higher than in a defined-contribution plan; that depends on age, income, actuarial factors, and current law. We do not state a typical dollar amount.
- Generally requires actuarial administration and annual funding
- Eligible employees generally must be covered; some owners consider using a cash balance plan alongside a 401(k)—confirm with your CPA, actuary, or TPA
- Who it may fit: some higher-income owners who can commit to funding—not a determination that it fits you
A 401(k) (including designs sometimes called “safe harbor”) is a plan type governed by current law. It is not listed here as a separate named firm service. Confirm testing, contribution, and design rules with your CPA or TPA.
What We Do
Plan design comparison
We can compare SEP, SIMPLE, solo 401(k), and cash balance plans in light of your income, employee count, and retirement savings goals. We coordinate the analysis with your CPA or TPA. Comparisons are educational; they are not tax advice and do not guarantee a contribution amount.
For cash balance and other defined-benefit plans, we do not administer the plan (that is a TPA function). We can discuss funding questions, contribution strategy, and how a pension account relates to other investments. Funding requirements are not guaranteed.
Investment management
If a plan is established and you engage us, we can manage investments as a fee-only fiduciary. Investment management fee for new assets in 2026: flat 1.00% annually of assets under management.
What We Don't Do
We do not earn commissions on plan products or investments.
We are fee-only. We do not earn commissions. The firm receives no portion of custodian commissions. Fee-only does not mean no conflicts: an asset-based fee creates an incentive to gather and retain assets.
We are not a third-party administrator (TPA).
Plan documentation, compliance, and annual filings are TPA functions. We can work with your TPA; we do not replace them.
This page is not tax or legal advice.
Plan-design discussion is financial planning / investment-related advice, not a tax opinion. Confirm tax consequences with your CPA or tax attorney. The firm also lists CPA coordination as a service; that is not a promise of tax-return preparation.
How We're Paid
Vital Investment Management, LLC is fee-only. We do not earn commissions. The firm receives no portion of custodian commissions.
Fee-only does not mean no conflicts. An asset-based investment management fee creates a conflict: we earn more when assets under management are higher. Fees are negotiable.
Investment management (new assets in 2026): flat 1.00% annually of assets under management. Fees can be deducted from the custodial account with written authorization. Some existing clients are on a legacy tiered schedule (1.50% / 1.00% / 0.75% / 0.50%).
Financial planning:
- Hourly: $300/hour
- Fixed-fee projects: minimum generally $1,500
- Ongoing planning: $200/month (basic); $500–$700/month (complex)
Firm Facts
- Formed in Colorado in 2019 (since 2019)
- Over $333 million in assets under management as of August 14, 2026 (not a performance claim)
- Custody: client assets held in the client's own name at a qualified custodian. The firm recommends Schwab Institutional (Charles Schwab & Co., Inc.). Schwab is independent and not affiliated with Vital Investment Management. The client decides.
- SEC-registered investment adviser (CRD #300811). Registration does not imply a certain level of skill or training.
About Dillon Goodman, CPA, CFP®
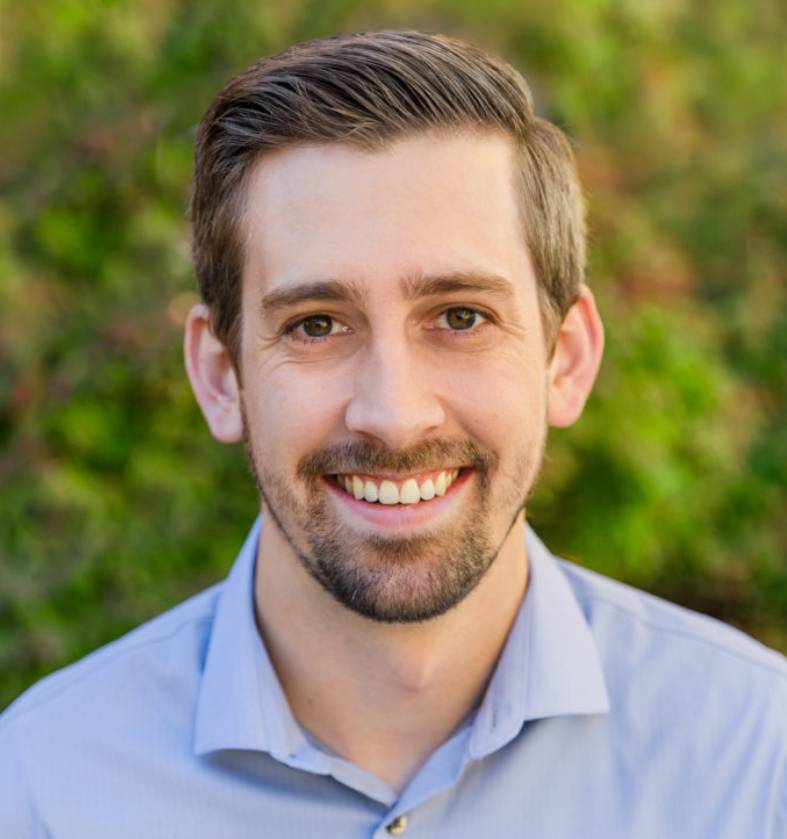
Dillon Goodman is a Colorado CPA (since November 14, 2019) and CERTIFIED FINANCIAL PLANNER™ professional (CFP®). He earned a B.S. in Accounting from Brigham Young University (2016) and an M.S. in Accounting from Idaho State University (2017). He worked as an audit associate at Deloitte & Touche (2017–2018) and as an accountant at Stephanie Packham CPA LLC. He has been a Financial Advisor at Vital Investment Management since March 2022 (CRD #7468576). Dillon leads the business-owner practice and serves clients from the Loveland office.
Book a call or send a message
30-minute intro call
Prefer a new tab? Book the 30-minute intro call
Or send a message
How It Works
1. Book a call or send a message
Book the 30-minute intro call, or fill out the short form above.
2. We discuss plan options
We'll review income, employee count, and retirement savings goals, then discuss how SEP, SIMPLE, solo 401(k), and cash balance plans may compare. We coordinate with your CPA or TPA. We do not guarantee contribution limits or tax results.
3. If both parties agree to work together
We can provide investment management as a fee-only fiduciary. You work with your TPA for plan administration and compliance.
Frequently Asked Questions
Is this a sales pitch?
The 30-minute intro call is a conversation. You'll describe your business and retirement goals, we'll explain how different plan types are generally described, and you decide if you'd like to take a next step. Booking a call does not create an advisory relationship.
What does it cost?
Plan-design discussion is financial planning: $300/hour or a fixed fee (minimum generally $1,500); ongoing planning $200/month (basic) or $500–$700/month (complex). Investment management for new assets in 2026 is a flat 1.00% annually of assets under management. Some existing clients are on a legacy tiered schedule (1.50% / 1.00% / 0.75% / 0.50%). No commissions. An AUM fee still creates a conflict because we earn more when assets under management are higher. Full fee schedule in our Form ADV.
Do you administer the plan?
No. A third-party administrator (TPA) handles plan documents, compliance, and annual filings. We can help you discuss plan design and manage investments if engaged; your TPA handles administration.
Can I combine a cash balance plan with a 401(k)?
Some owners consider using both; whether that is available or useful depends on facts and current law. It is not a way we can promise to maximize contributions. Confirm with your CPA, actuary, or TPA. We do not guarantee contribution amounts or tax results.
Where are my plan assets held?
Client assets are held in the client's own name at a qualified custodian. We recommend Charles Schwab & Co., Inc. (Schwab Institutional), which is independent and not affiliated with Vital Investment Management. The client decides. Plan-level custody can also depend on the plan's own arrangements; confirm with the TPA and custodian.
Do you guarantee returns?
No. We do not guarantee investment returns or results. Past performance is not indicative of future results.
Contact
Vital Investment Management, LLC
4045 St. Cloud Drive, Suite 220
Loveland, CO 80538
(970) 776-3316 (phone)
(970) 284-8555 (text)
info@vimadvisor.com
Hours:
Monday–Thursday 8:30 AM – 5:00 PM MT
Friday 8:30 AM – 3:00 PM MT